 High rental yieldUK-00011
Bermondsey: Zone 2 Apartments Completing in 2027
Bermondsey, London
- 2–3beds
- 2baths
- 76–90 m²
Off-plan · 2027
From€800,234
15 properties found
High rental yieldUK-00011Bermondsey, London
Off-plan · 2027
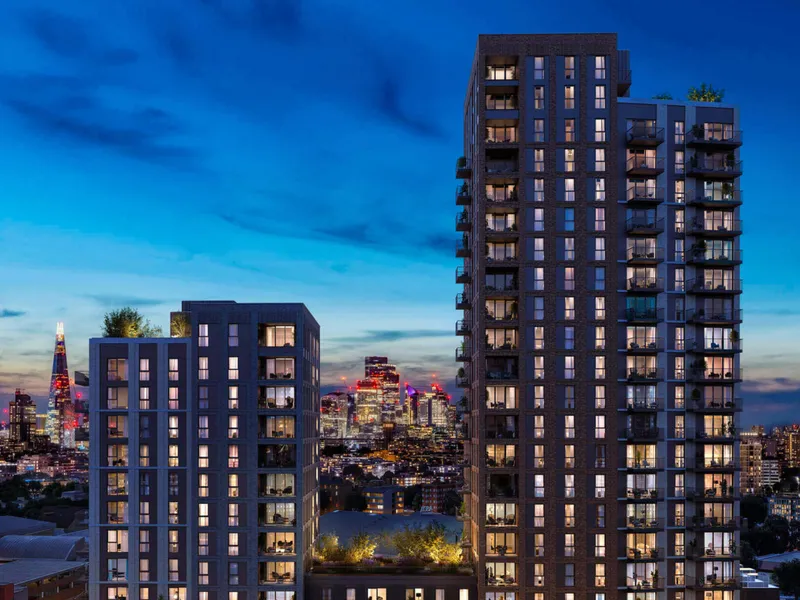 High rental yieldUK-00010
Bermondsey, London
Off-plan · 2028
 High rental yieldUK-00007
High Wycombe
Ready to move
Anyone searching for property for sale in United Kingdom listings is really making two decisions. The first is London or the towns an hour outside it. The second is the one most buyers meet late: whether you are buying the property itself, or the right to occupy it for a fixed number of years.
This page shows the stock across the country. The sections below exist so you can settle both questions before you make an offer rather than after.
London sits at the top of almost every overseas buyer's list, and there is a concrete reason for it. Tenant demand is not tied to a single industry, so the risk of a unit sitting empty is lower than elsewhere in the country, and the resale market functions at every price level.
What decides rent in London is not the building but the address and the time it takes to reach the centre. Two flats of the same size in two postcodes let for noticeably different money. Bermondsey and Hornsey are in the same city but do not serve the same tenant: one draws the young professional who wants to walk to work, the other draws the household looking for more floor area further north.
So before you open homes for sale in London, settle which tenant you are aiming at. The choice of flat follows from that, not the other way round.
The towns around London's edge form a separate entry level in the same uk property market. The tenant here is not a visitor but someone who works in London and lives outside it, which means rental demand tracks commuting time rather than the season.
Reading is the western end of the Elizabeth line, so it has a direct run into central London without a change, and that connection feeds the local tenant pool directly. High Wycombe and Guildford are smaller and more settled, and their stock leans further towards family houses than London's does.
The entry price is below London's, but the tenant profile is narrower too. , and show three quite different town characters.
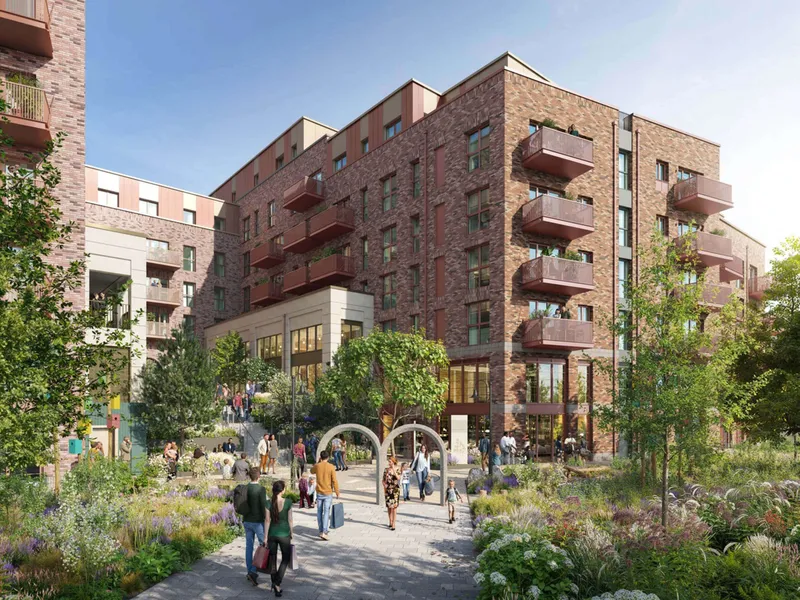 High rental yieldUK-00005
Guildford
Off-plan · 2029
 Payment planUK-00012
Bow, London
Ready to move · 2026
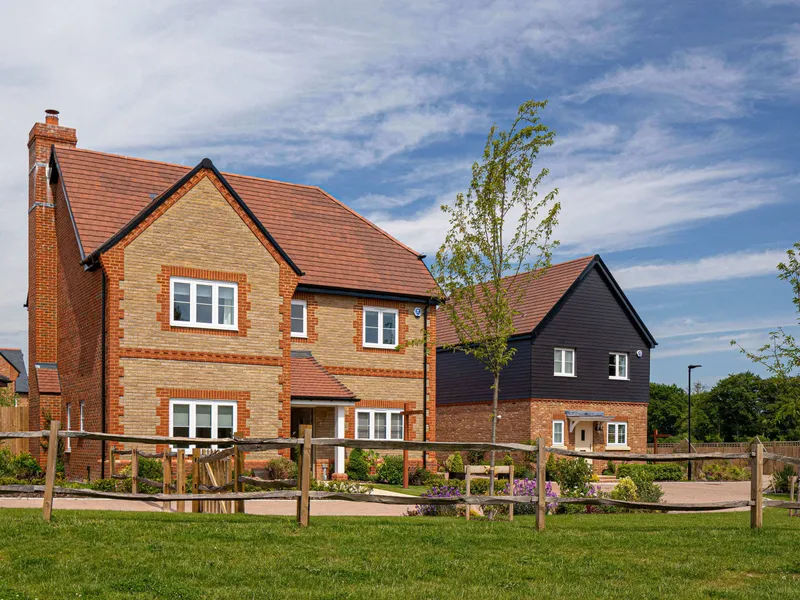 Payment planUK-00008
High Wycombe
Under construction · 2027
 Payment planUK-00006
Hornsey, London
Ready to move
 High rental yieldUK-00018
Staines Upon Thames
Ready to move
 High rental yieldUK-00017
Staines Upon Thames
Ready to move
 High rental yieldUK-00016
Milton Keynes
Under construction · 2028
 High rental yieldUK-00015
Milton Keynes
Under construction · 2027
 High rental yieldUK-00014
Camden, London
Under construction · 2026
 High rental yieldUK-00013
Camden, London
Ready to move
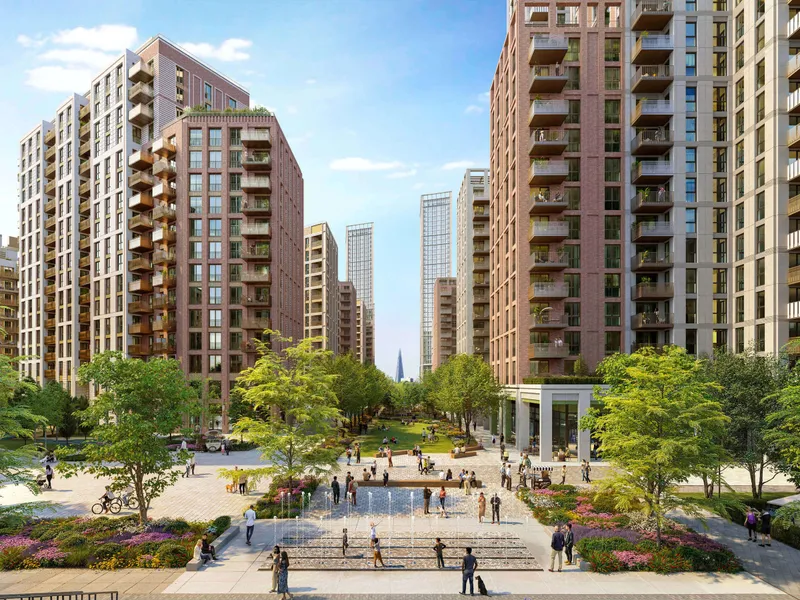 High rental yieldUK-00004
West Ham, London
Ready to move
 High rental yieldUK-00009
Reading
Ready to move
Ownership in the United Kingdom comes in two forms, and the gap between them catches out buyers from almost every other market. With freehold, the building and the land under it are yours indefinitely. With leasehold, in the government's own words, you only own the property for a fixed period of time, and ownership returns to the landlord when the lease comes to an end.
This is not a technicality. Most flats in the country are sold leasehold. Buy an apartment here and what you are usually buying is not the building but the right to occupy that unit for a stated number of years.
Three numbers settle it in practice: the years remaining on the lease, the annual ground rent, and the annual service charge. As the remaining term shortens, both resale and mortgageability get harder, which makes those three figures as decisive as the asking price.
The first is what sits on top of the asking price. Residential purchases in England and Northern Ireland attract Stamp Duty Land Tax, and an overseas buyer often pays two additions to it. A buyer who was not present in the UK for at least 183 days in the 12 months before the purchase pays 2 percentage points above the standard rates; that rule has applied since 1 April 2021 and the surcharge can be reclaimed within two years if the buyer later meets the residence test. Separately, if you own a residential property worth £40,000 or more anywhere in the world, the purchase counts as an additional property and the higher rates apply. For a buyer who already owns a home abroad, that means a first UK purchase is taxed as a second home. Scotland and Wales run their own taxes instead, so none of this applies there. Our United Kingdom buying guide works through the arithmetic.
The second is residency. Buying a home in the UK does not grant a residence permit. The country's investor route, Tier 1 (Investor), closed to new applicants on 17 February 2022, and the government's page now states plainly that no new application can be made. Even before it closed, residential property was not a qualifying investment; what qualified was share or loan capital in active UK registered companies. Owning property and holding status here are two separate tracks.
The decision really turns on who your tenant will be. In London you pay a higher entry price and get a wider, more durable pool of tenants. Outside it you pay less and tie yourself to a single source of demand, the person commuting into London. Both are coherent positions. What is not coherent is paying for one and expecting the returns of the other.
SmartDecision Properties asks the buyer for that answer at the first meeting. The town, the unit, the remaining lease term and the tax arithmetic are settled after it, not instead of it.